

Join Our Verizon EISP Webinar, Thursday, September 10 at 6 PM ET
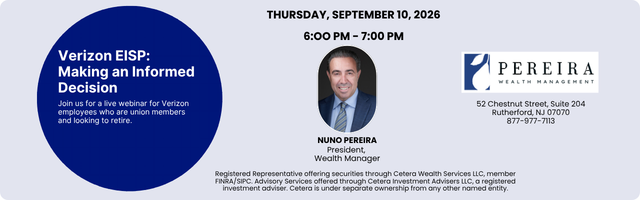
Verizon EISP: Your Guide Through the Decision
Specializing in Retirement Planning for Organized Labor Unions and Working Families. Proud supporter of the labor community and Associate Member of Amalgamated Local 426.
If you're a Verizon employee and a union member, there's a good chance you've either already received or will soon receive an Enhanced Income Security Plan (EISP) offer. These offers can be genuinely life-changing. But they come with a decision window that feels alarmingly short: typically 30 days.
In that window, you'll be asked to make some of the most significant financial decisions of your life: when to retire, whether to take a pension lump sum or monthly payments, how to handle your healthcare, and what to do with your 401(k). Get it right and you're set for a comfortable retirement. Get it wrong and there's no going back.
This guide breaks down what the EISP actually means, the choices you'll need to make, and how Pereira Wealth Management helps you make that decision with confidence, not pressure.
What Is the Verizon EISP?
An Enhanced Income Security Plan is Verizon's time-limited offer for eligible employees to voluntarily leave the company with enhanced separation benefits during a workforce reduction. It is not a layoff, but the offer is time-limited, and the terms vary by offer cycle, seniority, and employment classification.
A typical EISP package may include:
- A severance payment based on years of service
- An enhanced pension benefit or bridging to full pension eligibility
- Continued healthcare coverage for a defined period
- A reimbursement allowance for job placement, training, or relocation costs
What it does not include is a financial plan. That part is up to you, and it needs to happen fast.
You Have 30 Days. Use Them Wisely.
Pereira Wealth Management's suggested approach:
1. Get Organized
Gather pension estimates, 401(k) balance, healthcare details, and current beneficiary designations before your first advisor meeting.
2. See an Advisor First
Don't wait until week three. Come in before you've made any decisions, while all your options are still open.
3. Run Your Numbers
Lump sum break-even analysis, income projections, tax impact, and Social Security timing, modeled for your specific situation.
4. Align Legal Documents
Work with your attorney to update your will, trust, beneficiary designations, and power of attorney to reflect retirement.
Pension Decision: Lump Sum or Monthly Payment?
This is often the single biggest financial decision Verizon employees face when taking an EISP. Neither option is automatically better. The right choice depends on your health, your spouse's situation, your other income sources, and how comfortable you are managing a large sum of money on your own.
Advantages
- Guaranteed income for life; you can't outlive it
- Survivor benefit protects your spouse
- No investment decisions required
- Simple: the check arrives every month
Consider Carefully
- Fixed payment, less flexibility
- May not maximize value if health is a concern
- Cannot be passed as an asset to heirs
Advantages
- Large upfront capital, more flexibility
- Can invest and potentially grow the asset
- Can leave remainder to heirs
- Roll into an IRA to help plan for potential tax implications
- May suit better if health is a concern
Consider Carefully
- You bear all investment risk
- Risk of outliving the money if managed poorly
- Large tax event if not rolled correctly
Healthcare: The Gap Nobody Plans For
If you're under 65, this may be your biggest EISP risk
EISP Healthcare Bridge
Many packages include continued Verizon coverage for a defined period. Know the exact end date; it is critical.
COBRA
Continue Verizon coverage at full cost (102% of premium). Familiar coverage for up to 18 months but often expensive.
ACA Marketplace
Retirement is a qualifying life event. Enroll immediately. Costs vary widely by plan and your income level.
Spouse's Employer Plan
If your spouse has employer coverage, joining their plan is often the most cost-effective option available.
Medicare (Age 65+)
Understand how Parts A, B, C, and D interact with any Verizon retiree coverage you may retain.
Part-Time Work
Some retirees take part-time positions specifically for employer health benefits as a bridge strategy.
Social Security: When You Claim Matters
Delaying Social Security can be one of the most powerful strategies available to Verizon retirees. Here's what the numbers look like:
| Claim at Age | FRA = 66 | FRA = 67 | Impact |
|---|---|---|---|
| 62 | 75% of benefit | 70% of benefit | Maximum reduction |
| 65 | 93.3% | 86.7% | Still reduced |
| 66 | 100% | 93.3% | Full benefit (FRA 66) |
| 67 | 108% | 100% | +8% delayed credit |
| 68 | 116% | 108% | +16% delayed credit |
| 70 | 132% | 124% | Maximum: stop here |
Source: Social Security Administration. For illustration only.
Nuno helps you build a Social Security claiming strategy that coordinates with your pension and 401(k) income to help manage taxes and what you keep.
401(k): What Happens to Your Savings?
Moving your 401(k) incorrectly can trigger the need to plan for potential tax implications.
Option 1: Leave It With Verizon
Advantages: no immediate action required, may keep low-cost institutional funds, familiar investment lineup. Watch out for: limited investment flexibility, less control over strategy, RMDs still apply at age 73.
Option 2: Roll Over to an IRA
Advantages: full investment flexibility, consolidate all accounts, tax-deferred growth continues, more estate planning options. Watch out for: must execute correctly to avoid penalties, requires active management decisions.
Option 3: Take a Distribution
Advantages: immediate access to cash, may fund near-term needs. Watch out for: full amount taxable in year one, 10% penalty if under 59½, often the most expensive choice.
Estate Planning: Don't Let Retirement Break Your Plan
Beneficiary designations on retirement accounts and life insurance override your will. An outdated designation is one of the most common, and most avoidable, mistakes retirees make.
- Beneficiary Designations: review every retirement account, pension, life insurance, and bank account to confirm they match your current wishes.
- Will & Trust Review: retirement is a triggering event, so work with your attorney to update your will or trust.
- Power of Attorney: ensure you have a current financial and healthcare power of attorney naming the right people.
- Account Titling: joint tenancy, TOD designations, and trust ownership each have different outcomes for heirs.
- Legacy Planning: retirement is the right time to define what you want to leave behind, financially and otherwise.
Nuno coordinates with you and your attorney, ensures all financial accounts align with legal documents, and updates your plan as life evolves.
6 Common Mistakes That Could Cost You Everything
Every one of these is avoidable, but only if you know what to watch for.
Taking the lump sum without understanding the tax hit
If not rolled into an IRA immediately, your entire lump sum is taxable in year one. A $400K payout could push you into the 32–35% bracket.
Forgetting to update beneficiary designations
An ex-spouse or deceased parent could inherit your retirement account if designations aren't current. This overrides your will entirely.
Assuming the healthcare bridge lasts long enough
EISP healthcare has an end date. Miss the transition to COBRA, the ACA, or a spouse's plan and it could be costly and even leave you uninsured.
Rolling over the 401(k) incorrectly
An indirect rollover triggers mandatory 20% withholding. You have 60 days to replace the full amount, including the withheld portion.
Deciding based on what your coworker did
Your coworker's situation is not yours. Different age, savings, spouse, health. What was right for them may be wrong for you.
Waiting until week four of the decision window
By week four, options have narrowed. Members who navigate EISP best are the ones who prepare before the offer even arrives.
The Pereira Wealth Management Process: Simple, Coordinated, Lasting
Discovery Call
Nuno learns your situation (age, pension status, savings, goals, family) before you're holding any paperwork. This sets the foundation.
Run the Numbers
Lump sum vs. annuity analysis, 401(k) rollover strategy, Social Security timing, healthcare timeline, and projected retirement income.
Coordinate the Team
Nuno works with your estate attorney (or refers you one), aligning legal documents, designations, and account titles with your new plan.
Implement the Plan
Once you've decided, Nuno helps execute the rollover, update designations, and put your income strategy in motion smoothly.
Ongoing Agreement
Life changes. Nuno reviews your plan at every annual meeting, and whenever a life event occurs. You'll never face a major decision alone.
Schedule a Consultation
Schedule a no-obligation conversation with Nuno. The employees who navigate this best are the ones who prepare early.
Office: 877-997-7113 · Cell: 914-703-1275 · nuno@pereirawm.com
Before deciding whether to retain assets in an employer-sponsored retirement plan or roll them into an IRA, investors should consider various factors including, but not limited to, investment options, fees and expenses, services, withdrawal penalties, protection from creditors, required minimum distributions, and tax consequences. The information in this material is not intended as tax or legal advice. Please consult legal or tax professionals regarding your individual situation.